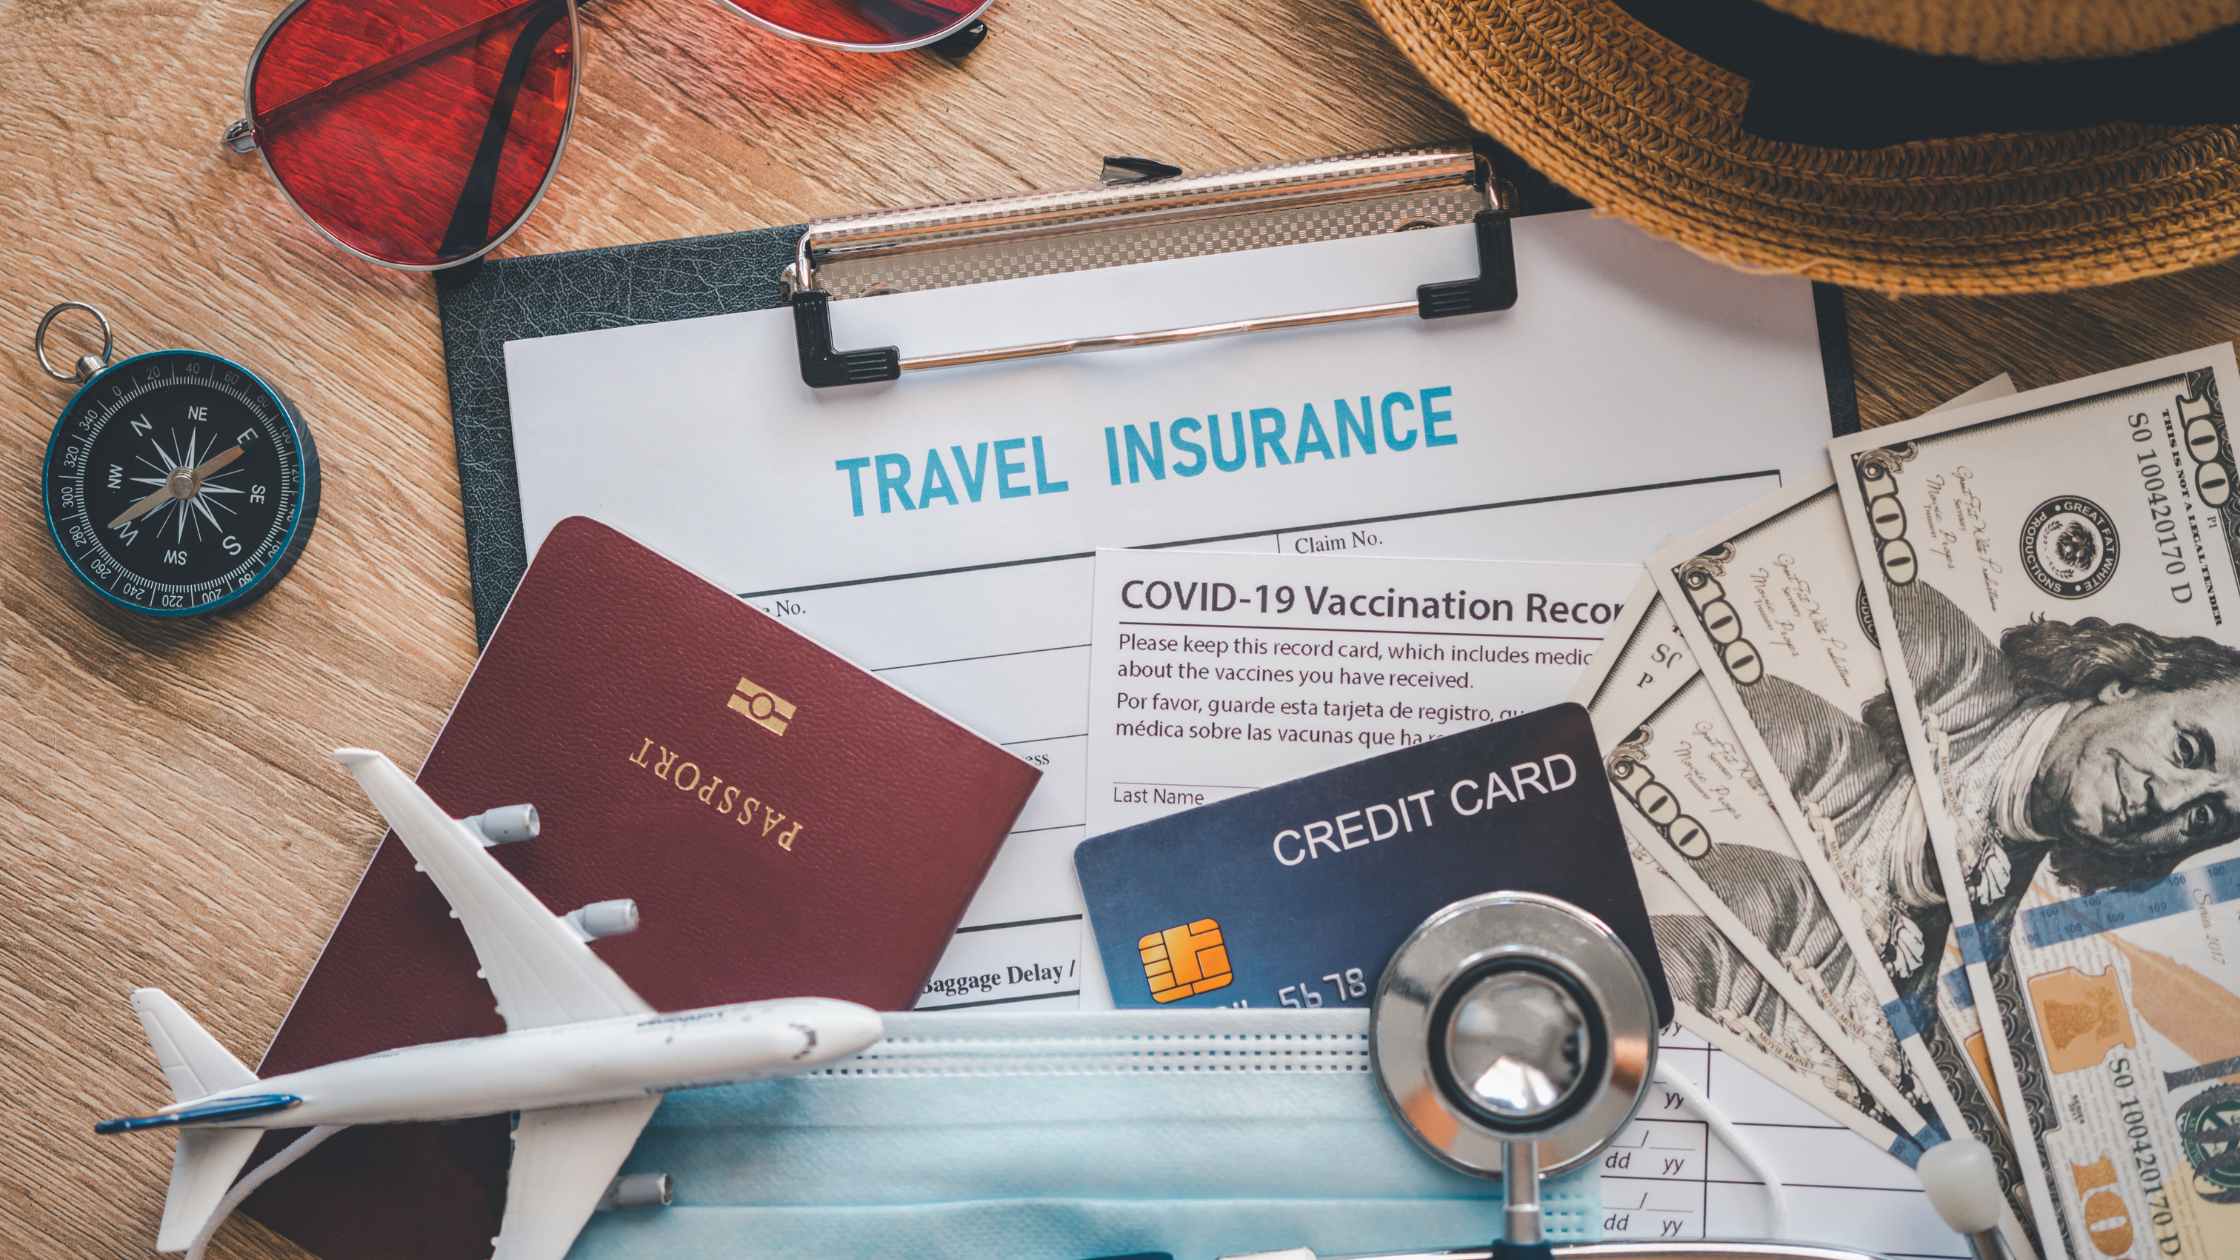
No one plans to break a bone while exploring the historic streets of Rome, nor does anyone anticipate a sudden severe cardiac event while cruising through the Caribbean. Yet, thousands of international jet-setters find themselves in foreign hospitals every year, facing not just medical trauma, but astronomical financial liabilities.
When you cross international borders, your domestic health insurance coverage almost always stops at the shoreline. For instance, the United States government explicitly states that it does not pay medical costs for citizens abroad, and programs like Medicare or Medicaid offer zero cross-border coverage. This massive financial exposure is precisely why emergency medical travel insurance has evolved from a luxury add-on into an absolute non-negotiable component of modern trip planning.
The guide below explores the intricate mechanics of travel medical insurance, uncovering hidden policy exclusions, explaining multi-million dollar evacuation strategies, and showing you exactly how to maximize your Google-backed search engine visibility for this lucrative insurance niche.
1. What is Emergency Medical Travel Insurance?
At its core, emergency medical travel insurance is a short-term, supplemental health policy specifically engineered to safeguard you against unexpected illnesses, acute injuries, and catastrophic medical events that occur outside your home country. It acts as a financial buffer between you and foreign healthcare systems, ensuring you receive world-class treatment without exhausting your life savings.
Unlike comprehensive travel protection packages that prioritize financial refunds for lost baggage or missed flight connections, emergency medical travel insurance puts human health first. It is designed solely to absorb the immediate, volatile costs of urgent clinical interventions, ranging from prescription medications for severe food poisoning to intricate, emergency trauma surgeries.
The Critical Gap in Domestic Insurance
The most pervasive misconception among global travelers is that their existing commercial health plan provides global safety nets. It does not. Most domestic insurance networks operate within strict geographic boundaries. Even if your domestic insurer offers “out-of-network emergency care” while you are traveling out of state, these benefits rarely cross ocean borders, and they almost never cover the logistical nightmare of international medical transport.
Furthermore, international medical facilities operate under vastly different regulatory and financial frameworks than your hometown clinic. Many foreign hospitals require upfront cash deposits or concrete proof of specialized travel insurance before they will even admit an international patient for non-life-threatening treatments. Without dedicated emergency medical travel insurance, you are forced to navigate these high-stakes financial barriers completely on your own.
2. Core Coverages within Travel Medical Policies
When purchasing an emergency travel medical plan, it is vital to know exactly what your premium is protecting. Premium plans often feature maximum coverage caps ranging from $50,000 to upwards of $8,000,000.
+-----------------------------------------------------------------------+
|                 COMPREHENSIVE TRAVEL MEDICAL CAPS                     |
+-----------------------------------------------------------------------+
| [Emergency Room & Inpatient] --------------> Up to $2,000,000 Max    |
| [Emergency Medical Evacuation] ------------> Up to $1,000,000 Max    |
| [Emergency Dental Interventions] ----------> Up to $1,000 Max        |
+-----------------------------------------------------------------------+
The components detailed below form the foundation of a high-quality travel health framework:
A. Emergency Medical Treatment
This is the primary engine of your policy. It covers direct clinical expenses incurred due to a sudden, unforeseen medical crisis during your journey. Eligible expenses typically include:
-
Hospital room and board fees during involuntary inpatient stays.
-
Intensive Care Unit (ICU) monitoring and specialized nursing care.
-
Emergency room services, diagnostic X-rays, and lab examinations.
-
Intravenous medications, local ambulance transport, and physician consultation fees.
B. Emergency Medical Evacuation
If you suffer a catastrophic injury in a remote geographic region—such as a deep compound fracture while trekking through Southeast Asia—local medical outposts might lack the diagnostic machinery or sterile environments required to treat you safely. Emergency medical evacuation coverage pays for the logistical arrangements and transport costs to fly you via an advanced air ambulance to the nearest state-of-the-art medical center. Because private medical airlifts can easily cost upwards of $100,000 to $250,000, this single benefit can prevent immediate personal bankruptcy.
C. Medical Repatriation Services
While evacuation moves you to the nearest capable hospital, medical repatriation focus shifts toward returning you to your home country. If your medical team determines that your recovery will require months of specialized, round-the-clock therapy, repatriation coverage organizes and finances your trip home. This often involves booking multiple commercial airline seats to accommodate a flat stretcher, along with hiring a certified medical escort—such as a critical care nurse or physician—to manage your vitals and intravenous medications mid-flight.
D. Emergency Dental Procedures
Standard travel medical insurance does not cover routine cleanings or cosmetic dental adjustments. However, it does provide acute relief for sudden, debilitating dental emergencies. If you suffer an unexpected dental abscess or fracture your front teeth in an accidental fall, this provision covers the immediate clinical expenses required to relieve your pain and stabilize your jaw line, usually capped between $500 and $1,500 per traveler.
E. Accidental Death and Dismemberment (AD&D)
Though uncomfortable to consider, a comprehensive policy must account for the worst-case scenarios. AD&D functions similarly to a short-term life insurance policy. It provides a designated cash payout to your chosen beneficiaries if you suffer a fatal accident or experience a permanent, life-altering dismemberment (such as the loss of sight or limbs) while utilizing a public commercial transport carrier during your covered journey.
3. Hidden Exclusions: What Is Not Covered?
The true value of an insurance policy is defined as much by what it excludes as by what it covers. To avoid denied claims, every global explorer must carefully read the fine print of their policy document.
Critical Warning: Never assume an insurance policy covers every medical event. Failing to disclose a pre-existing condition or engaging in a banned high-risk sport can completely invalidate your coverage, leaving you solely responsible for millions in foreign medical debt.
The major exclusions found across standard industry offerings include:
A. Pre-Existing Medical Conditions
A pre-existing condition refers to any health issue, chronic illness, or physical injury for which you received medical advice, diagnostic testing, or prescription medication adjustments prior to buying your policy. Standard budget travel insurance plans explicitly exclude these conditions from coverage.
However, many premium insurers provide a Pre-Existing Condition Exclusion Waiver. To qualify for this crucial waiver, you generally must meet the following criteria:
-
You must purchase your travel medical policy within a strict time-sensitive window (usually 14 to 21 days) after making your very first initial trip deposit.
-
You must be medically stable and physically fit to travel on the exact day you buy the policy.
-
You must insure 100% of your total, non-refundable prepaid trip expenses.
B. High-Risk Adventure Sports and Activities
If you plan to paraglide over the Swiss Alps, scuba dive deeper than 30 meters in the Great Barrier Reef, or mountaineer up ice cliffs, a basic travel medical policy will not protect you. Insurers categorize these pursuits as high-risk extreme sports. To stay safe, you must purchase a specialized adventure sports rider or select an outdoor-focused provider like World Nomads, which explicitly adds hazardous sports back into the coverage umbrella.
C. Substance-Induced Incidents and Intoxication
If you experience an emergency room admission because you sustained a concussion after consuming excessive alcohol at an international beach party, your insurer will almost certainly deny your claim. Any injuries or health crises that arise directly from operating under the influence of alcohol, non-prescribed narcotics, or self-inflicted chemical hazards are universally excluded from travel insurance compensation.
D. Routine, Non-Emergency Healthcare
Travel medical insurance is strictly reactive, designed only to address sudden, unpredictable trauma and illness. It cannot be used to cover scheduled check-ups, ongoing physical therapy, routine prenatal care, elective cosmetic surgeries, or refilling maintenance medications that you simply forgot to pack before leaving home.
4. Single-Trip vs. Multi-Trip Insurance Plans
Choosing the right structure for your emergency travel medical insurance depends heavily on your annual travel patterns. Selecting the incorrect type can result in paying unnecessarily high premiums or accidentally traveling without active coverage.
| Feature Comparison | Single-Trip Insurance Plans | Multi-Trip Annual Plans |
| Ideal User Profile | Occasional vacationers or single-destination holidaymakers. | Frequent business fliers, digital nomads, and serial expats. |
| Coverage Duration | Tailored to match the exact start and end dates of one trip. | Covers an unlimited number of trips across a full 12-month window. |
| Per-Trip Day Limits | Usually covers extended journeys lasting up to 180 continuous days. | Each individual trip is capped at a set limit (e.g., 30, 45, or 90 days). |
| Premium Structure | Calculated dynamically based on your specific trip length and cost. | A single, predictable flat annual fee paid upfront. |
Single-Trip Insurance Frameworks
A single-trip policy protects one specific itinerary from the moment you leave your front door until you return home. It is highly customizable, allowing you to scale coverage limits upward if you are visiting countries with famously expensive healthcare infrastructure, such as the United States or Singapore. Once you return home, the policy naturally expires.
Multi-Trip Annual Frameworks
For travelers who cross borders three or more times a year, an annual multi-trip plan is highly cost-effective. Instead of purchasing separate coverage for every quick weekend getaway or unexpected corporate flight, you pay one annual fee for continuous year-round peace of mind.
However, you must monitor the maximum trip length restriction. While an annual policy covers you for 365 days, it requires you to return to your home country after a set duration (often 30 to 45 consecutive days) before your coverage reset allows you to embark on your next trip.
5. Step-by-Step Guide to Purchasing a Policy
Securing the right policy requires a methodical approach. Follow this step-by-step process to ensure you purchase a robust plan that leaves zero room for claim denials:
6. Filing an Emergency Medical Claim Abroad
If you experience an unexpected medical emergency while traveling, navigating the claims process correctly is vital to ensuring your expenses are fully reimbursed. The steps below detail how to manage a medical crisis effectively:
Immediate Communication with Your Insurer
The moment you or your travel companion are stabilized at a medical facility, you must immediately contact your insurance provider’s 24/7 Emergency Assistance Center. Do not wait until you are discharged to inform them. Most major insurers maintain dedicated, multilingual teams that specialize in communicating directly with international hospital administrators.
Your insurer can coordinate a direct payment arrangement, which allows the hospital to bill the insurance company directly. This prevents you from having to pay thousands of dollars out-of-pocket on your personal credit card.
Essential Documentation Checklist
If a foreign medical clinic does not support direct billing, you will need to pay for your treatments upfront and submit a comprehensive reimbursement claim later. To ensure your claim is approved without delay, you must collect and submit the following primary evidence:
-
Itemized Medical Invoices: Comprehensive bills showing every clinical charge, doctor consultation fee, and medication administered.
-
Official Diagnostic Reports: Signed clinical statements from the treating physician detailing your exact diagnosis and the cause of your medical emergency.
-
Original Payment Receipts: Explicit credit card statements or cash receipts confirming the exact amounts you paid to the facility.
-
Proof of Travel Itinerary: Your original airline boarding passes or cruise documentation confirming that the emergency occurred within your covered travel dates.
7. Maximizing Search Engine Performance for Travel Insurance Content
For digital publishers, travel bloggers, and financial content creators, the “emergency medical travel insurance” niche represents one of the highest-paying Cost-Per-Click (CPC) domains within Google AdSense. Because insurance customer acquisition values are exceptionally high, providers are willing to pay top dollar for targeted web traffic.
To rank this comprehensive article on the first page of major search engines, you must execute a calculated Search Engine Optimization (SEO) strategy.
Intent-Driven Keyword Distribution
To build search topical authority, integrate high-value long-tail keywords smoothly across your article’s structural headings and body text. Focus your deployment around these high-volume search phrases:
-
Primary High-Value Target: Emergency medical travel insurance (Deploy within the main H1 title and naturally across your opening paragraph).
-
Secondary Logistical Intent: International travel health coverage and medical evacuation insurance plans.
-
Transactional Search Variances: Best travel insurance for pre-existing conditions and affordable multi-trip annual plans.